Lumepay, the Cape Town-based cross-border payments company built for SMEs, corporates and institutions that need to move money across Africa and into global markets, is launching in Kenya this month, the first market on its African expansion roadmap. It arrives with regulatory clearance in hand, in the form of a letter of no objection, and a licensed local partner, and it will be on the ground at the Africa Blockchain Fest in Nairobi from 15 to 17 October.

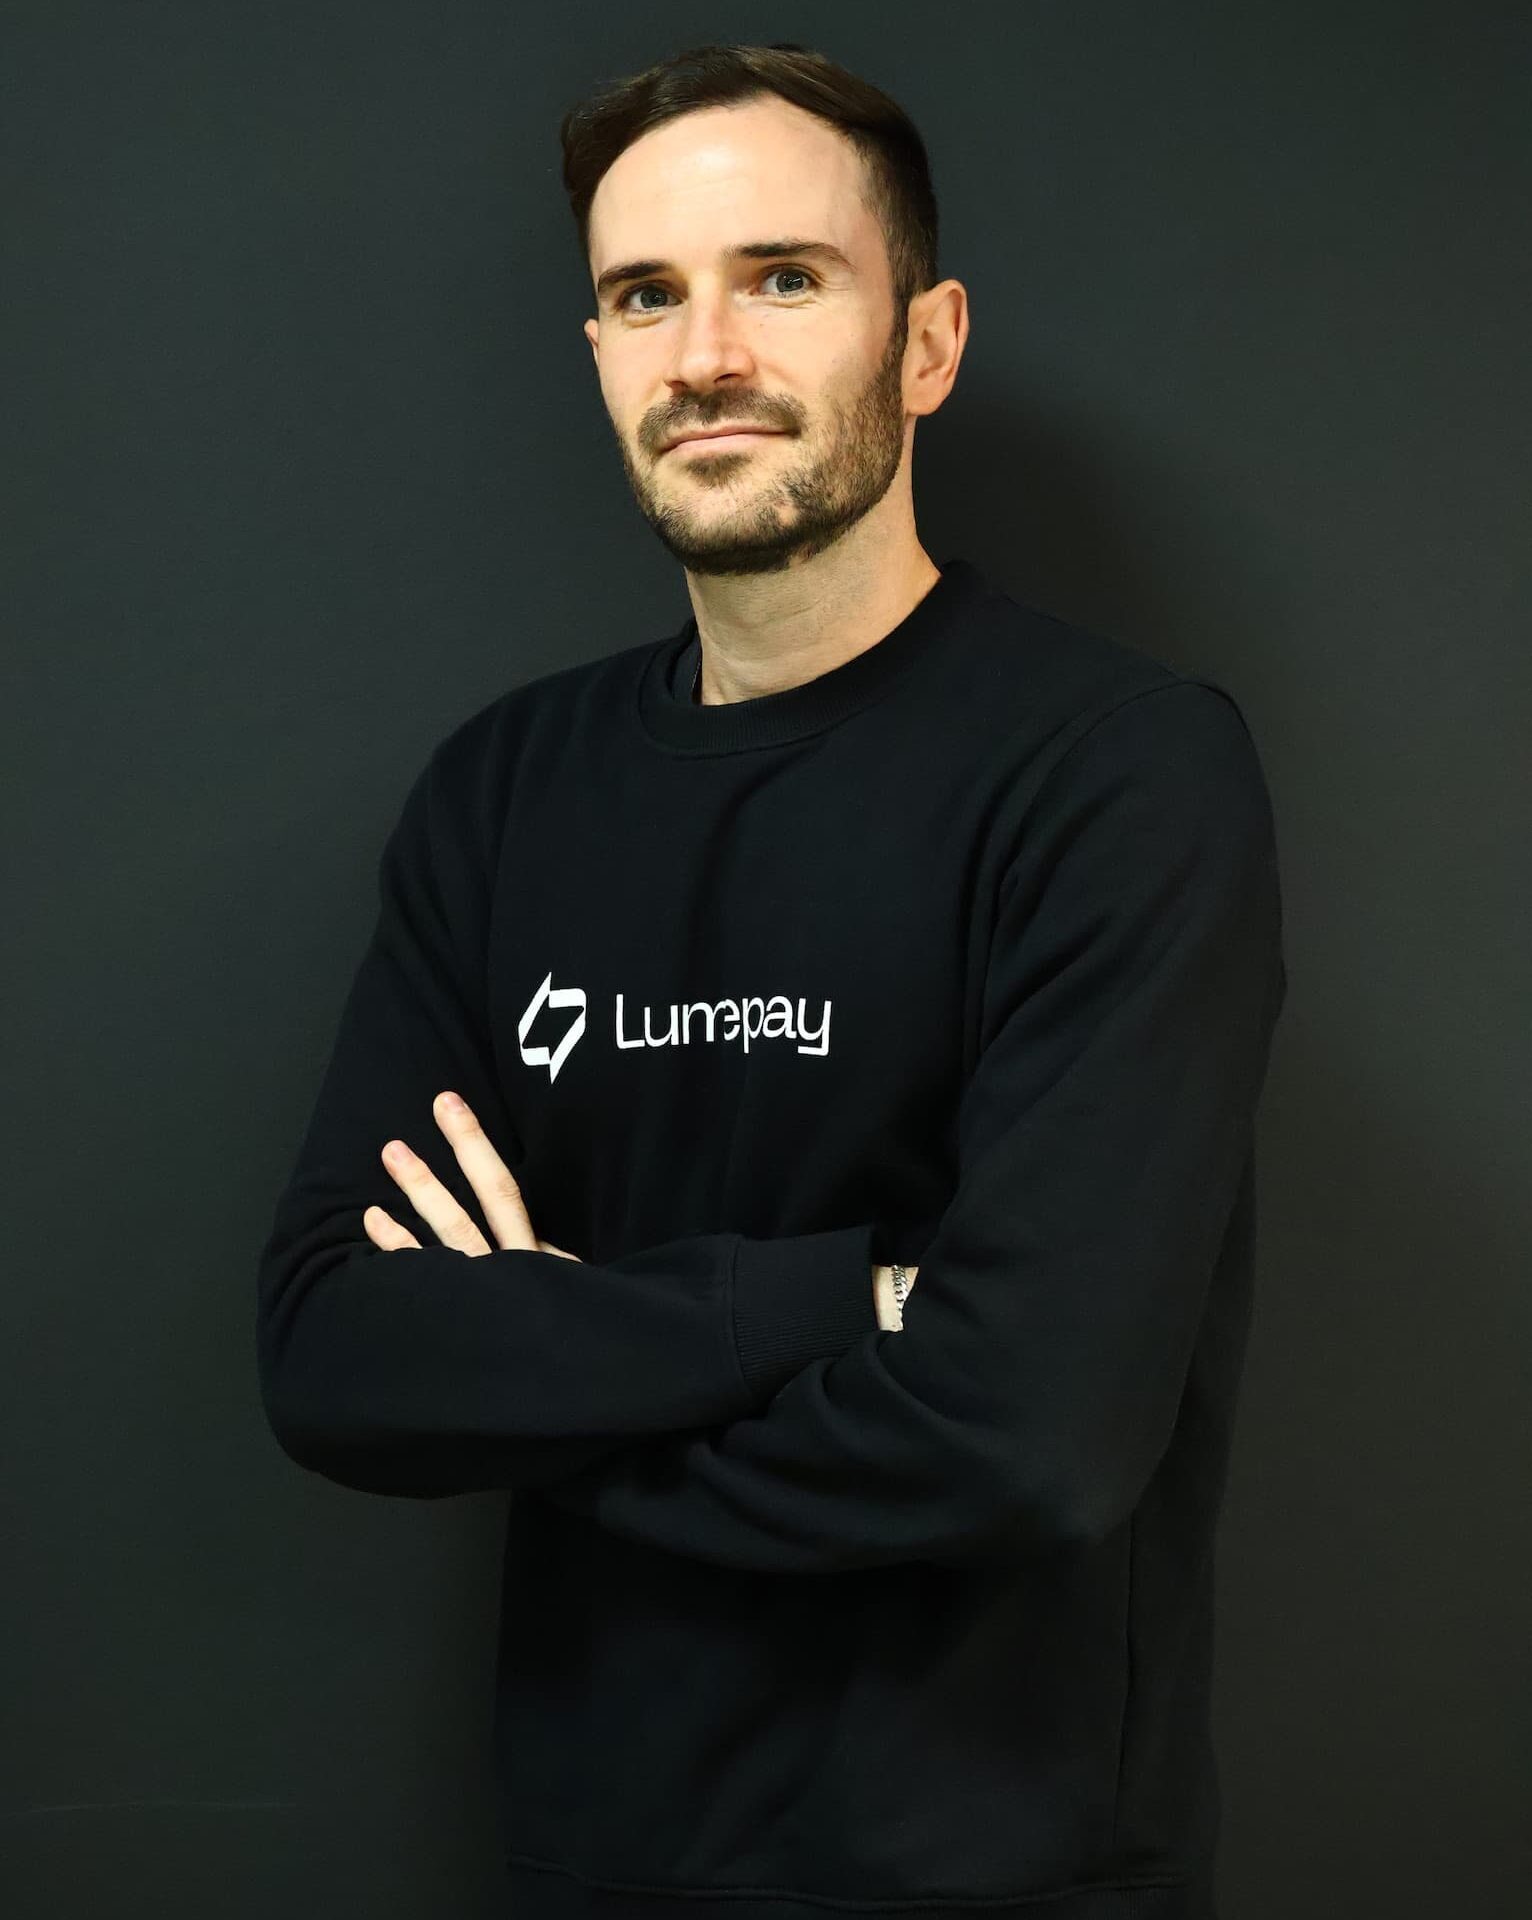
Its chief operating officer, Luc Varejes, spoke to The Fintech Times about the structural problem Lumepay is built to solve, why Kenya is a hub rather than a single-market play, what the launch means in practice for Kenyan businesses, and where the company wants to be in five years.
Fixing the plumbing
For Varejes, the gap Lumepay is closing is not a product gap but a structural one. “For decades, moving value across African borders has meant going through a fragmented web of correspondent banks, multiple intermediaries and layered currency conversions. Each step adds cost, delay and uncertainty,” he said. By Lumepay’s estimate the result is a system that costs African businesses around five billion dollars a year in inefficiencies, “and for a business, that shows up as tied-up working capital, unpredictable settlement times and pricing that is hard to plan around.”
The company’s answer is to work on the infrastructure itself rather than the interface on top of it. “Our focus is on fixing the plumbing,” Varejes said. “We are building regional payment corridors and deep liquidity pools across the SADC and WAEMU regions, which strengthens Africa’s financial connectivity both within the continent and with the rest of the world.” Operationally that means combining “the reach and reliability of traditional payment infrastructure with the speed and efficiency of stablecoin rails”, which he said gives businesses “faster settlement, more competitive and predictable pricing, and the confidence that their payments will arrive when they need them to.”
Why Kenya, and why now
Varejes gave three reasons for choosing Kenya as the first stop. The first is trade. “The South Africa-Kenya corridor is a fastest-growing trade route. South African and Kenyan businesses are trading with each other more than ever, but the payment infrastructure hasn’t kept pace,” he said. “Settling a supplier invoice between Johannesburg and Nairobi still too often means going through correspondent banks in another currency, with the delays and costs that come with it.”
The second is geography. Kenya has one of the most mature digital payments ecosystems in the world, driven largely by mobile money, and strong regional links into Uganda, Tanzania, Rwanda and beyond. “For us, Kenya isn’t a single-market play,” Varejes said. “It’s the hub that connects our southern and western corridors to the broader East African Community.”
The third is that the volumes already exist. He pointed to the 2025 remittances household survey by the Kenya National Bureau of Statistics and the Central Bank of Kenya, which found that Kenyan households received an estimated KSh931.8 billion from abroad between June 2024 and May 2025, while residents sent KSh40.5 billion out of the country over the same period. “And that’s only the household side,” he said. “Money crosses Kenya’s borders every day to finance trade, pay suppliers and fund investment. The demand for faster, more cost-effective cross-border payments is clear.”
As for the timing: “The market is ready, and so are we. With regulatory clearance in place and a licensed local partner, we can enter Kenya with the right foundations to serve businesses from day one.”
What the launch means in practice
Asked what Kenyan businesses will actually be able to do from launch, Varejes described a set of concrete use cases. A business can pay international suppliers in the supplier’s own currency, such as US dollars or Chinese yuan, so an SME settling offshore invoices “can settle in each supplier’s preferred currency faster, and without costly conversions. Suppliers get paid in their expected currency.”
Businesses operating in Kenya can also access US dollars instantly. “No more funds stuck in transit for months,” he said. “Businesses can confidently grow across Africa, with the certainty that money moves.” A merchant making bulk payments can pay “quickly and compliantly across many recipients and currencies at once, settling hundreds of payouts in a single flow.” Alongside that sit diversified ways to send and receive local and other currencies, including USDT on-ramps and off-ramps and M-Pesa, and payment links.
Where Lumepay sits
The distinction Varejes draws from the rest of the market starts with the rails. “We use our own stablecoin infrastructure, built and supported by us, to make every payment more efficient,” he said. Lumepay’s own account of its position is that its advantage lies in developing strong traditional, digital (stablecoin-enabled) and FX capabilities that together compound in value: operating depth across traditional banking rails, stablecoins and FX, where the market tends to offer one or two of the three, and “going to market with all three, from the get-go, with deep African context.”
He is candid that the hardest part is not technology but liquidity. “Africa has its unique challenges: FX liquidity limitations at financial institutions, settlements that take weeks, laborious compliance processes. Deep liquidity that moves and routes with efficiency is key to moving value, and takes years to build up. We’ve already built it and are actively growing and optimising our liquidity.” Every founder, he added, has personally set up, scaled or led functions inside cross-border payments businesses. “We are accelerating, not researching.”
In Varejes’s description, Lumepay sits across the full transaction lifecycle. “Currency exchange, liquidity management, clearing, payments collections and disbursements, and settlement infrastructure, all within a single licensed perimeter. Customers operate through one integrated platform rather than coordinating across multiple vendors and intermediaries.” The role, he said, extends beyond being a conversion or pay-out venue: “Lumepay is the end-to-end cross-border solutions and infrastructure layer that supports execution, post-trade processing, reconciliation, and settlement across multiple rails and jurisdictions.”
That is also how he frames the company’s relationship with the incumbents. “The ecosystem we are building is not about replacing every existing provider, it is about creating the connective infrastructure that lets the broader financial system operate seamlessly, efficiently, and transparently across borders.”
Lumepay’s competitive advantage
According to Lumepay, its competitive position rests on combining traditional banking infrastructure, stablecoin-enabled payment rails and foreign exchange capabilities, alongside experience operating in African markets.
- Business model and infrastructure. Lumepay says its team has experience across traditional banking, stablecoins and FX. Its strategy is to bring these capabilities together in a single offering, rather than relying on one or two components.
- Africa-specific understanding. The company identifies limited FX liquidity, lengthy settlement processes and demanding compliance requirements as challenges in African cross-border payments. It says developing deep, efficiently routed liquidity is central to addressing them.
- Execution and speed to market. Lumepay says its founders have established, scaled or led cross-border payments functions, bringing operational experience and existing capabilities to the business.
- Stablecoin-enabled settlement. The company views stablecoins as a tool for moving value and expects broader adoption as regulation and access develop. It argues that liquidity, licences and connections to traditional banking remain important to scaling these services.
The next five years
Kenya is the first market on the roadmap, and Varejes set out the five outcomes Lumepay is building towards over the next five years: a diversified customer base across markets and sectors, with reach and regular payments activity across key African markets; reliable and regulated multi-corridor payment infrastructure, liquidity and market coverage; the strongest wholesale pricing and deepest liquidity across all African currency pairs; key licences across all major African markets; and a robust, high-speed stablecoin settlement layer.
Stablecoin adoption, he argued, strengthens rather than threatens that position. “As it becomes more regulated and accessible, more players will naturally try capture the opportunity, but we will be at the forefront of the ecosystem and capabilities built around it to successfully scale: deep, diversified liquidity across corridors; the licensing to operate legally in each market; and the bridge between stablecoin and traditional banking that moves value reliably.”
On the ground in Nairobi
Lumepay will be at the Africa Blockchain Fest from 15 to 17 October, and Varejes sees the event as the right place to start. “It brings together the people building the next phase of African finance and trade. We strongly believe in being on the ground so we can hear directly from the people we aim to serve.”
The message he wants people to leave with is a simple one. “Lumepay’s focus is helping African businesses grow beyond their home markets without payment friction getting in the way.”
The post Lumepay’s Luc Varejes on fixing the plumbing of African cross-border payments, starting in Kenya appeared first on The Fintech Times.